Paycheck Deductions Explained: Where the Money Goes Before Take-Home
The gap between your salary and your bank deposit isn't one tax. It's a queue — and the order of the queue changes the maths.
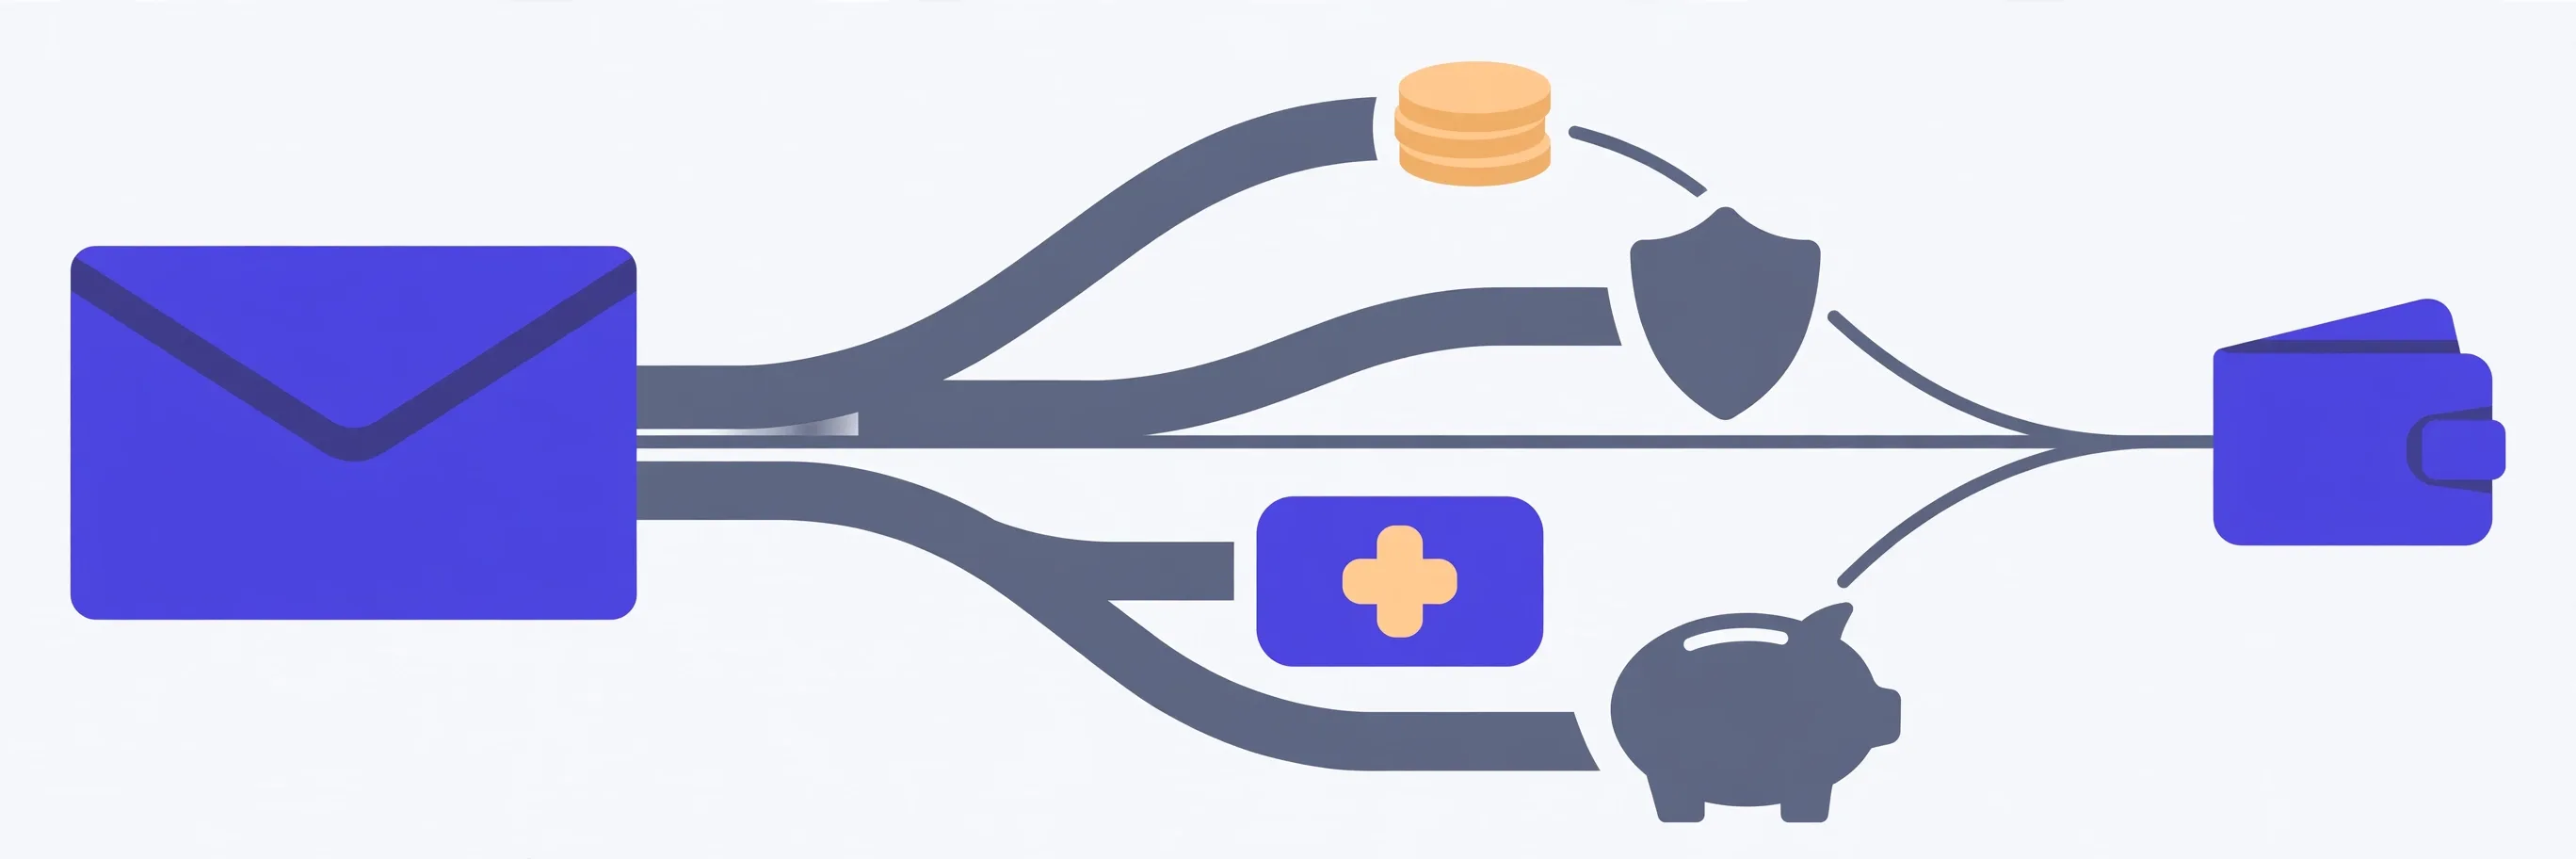
A US paycheck is gross pay filtered through layers, each on a different base. Pre-tax items come off first, but not alike: a traditional 401(k) deferral (2026 cap $24,500) escapes income tax yet not FICA, while pre-tax health premiums usually escape both. FICA then takes a flat 7.65% — Social Security 6.2% up to the 2026 wage base of $184,500, plus Medicare 1.45% on all wages. Federal tax applies the marginal brackets only to what's left after the standard deduction ($16,100 single, 2026). State tax follows on its own terms — or not at all in nine states. Mechanism only; not tax or financial advice.
Gross is the starting line, not the answer
Your offer letter says one number. Your bank account receives a smaller one. The gap isn't a mistake, and it isn't one tax either — it's a queue of deductions, each with its own rules, taken in a set order.
That order is the whole story. Some amounts come off before any tax is worked out. Some taxes ignore those early deductions completely. Others are calculated only on what's left. Read a stub top to bottom and you're watching money pass through the layers in sequence: gross, pre-tax deductions, payroll taxes, income taxes, post-tax items, and finally net pay.
This guide walks through the mechanism for US wages, using the tax year 2026 figures the calculator below runs on. It isn't tax or financial advice; your stub and W-4 are the authority on your pay.
First off the top: pre-tax deductions
A traditional 401(k) contribution comes out before federal and — in most states — state income tax is calculated. Defer $5,100 and that $5,100 isn't in the income the brackets hit this year. For 2026 the deferral cap is $24,500, plus an extra $8,000 catch-up at age 50 or over. But here's the catch people miss: a 401(k) deferral does not reduce Social Security or Medicare tax. Those are charged as if the deferral never happened.
Pre-tax health premiums are broader. Run through an employer's cafeteria plan, they usually escape income tax and payroll tax. So two deductions under the same "pre-tax" heading can shrink different tax bases — a distinction that explains a lot of stub arithmetic that looks wrong at first glance.
FICA: the flat slice that ignores your 401(k)
Social Security and Medicare together are FICA, and for most employees they take a flat 7.65%. Social Security is 6.2%, charged only up to a yearly wage base — $184,500 for 2026; past that cap it stops for the year. Medicare is 1.45% on all wages, no cap, plus an extra 0.9% on wages above $200,000 single or $250,000 married filing jointly.
Flat means flat. FICA doesn't care about your filing status, standard deduction or bracket, and it's charged after pre-tax health premiums but before any 401(k) deferral is subtracted. Your employer pays a matching 7.65% on top — that half never shows on your stub.
Income tax: brackets applied to what's left
Federal withholding starts from a smaller pile: gross, minus pre-tax health premiums, minus your 401(k) deferral. Then the standard deduction comes off — for 2026, $16,100 single, $32,200 married filing jointly, $24,150 head of household. Only what remains runs through the brackets, and the brackets are marginal: a rate applies to the slice inside its band, not to everything you earn. Crossing into a higher band never taxes your whole pay at that rate.
State tax is its own system bolted on afterwards. Some states charge a flat rate, some run graduated brackets off their own deduction, and nine levy no broad-based tax on wages in 2026: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington and Wyoming. Local income taxes exist in some cities; the calculator below doesn't model them, and says so.
One worked example pulls it together — it's the example the calculator below is checked against. Single filer, California, $85,000 salary, paid every two weeks, 6% ($5,100) into a 401(k) and $120 per paycheck ($3,120 a year) in health premiums:
| Line | Base | Amount |
|---|---|---|
| Social Security (6.2%) | $81,880 — gross minus health premiums; the 401(k) doesn't reduce it | $5,076.56 |
| Medicare (1.45%) | Same $81,880 | $1,187.26 |
| Federal income tax | $60,680 — after premiums, the 401(k) and the $16,100 standard deduction | $8,061.60 |
| California state tax | $70,880 — after California's $5,900 standard deduction, minus its $158 exemption credit | $2,807.52 |
| Take-home | $85,000 minus premiums, 401(k) and all four tax lines | $59,647.06 a year — $2,294.12 per paycheck |
Run the identical salary in Texas and the state line drops to $0, so take-home rises by exactly that $2,807.52. That's the state effect, isolated.
Withholding isn't the tax itself
One last distinction, and it's the one that produces April surprises. The income tax on each stub is withholding — an estimate shaped by the W-4 you filled in. Your actual tax is settled when you file: withheld too much and the difference comes back as a refund; too little and you owe. Neither outcome means the stub was wrong. Post-tax items — a Roth contribution, a garnishment — sit below all of this and change net pay without changing any tax line above them.
Reading your own stub, step by step
- Start at gross and multiply up to a year — every cap and bracket here is an annual figure, and stubs hide that.
- Find the pre-tax block. Separate the 401(k) line from health premiums; remember they shrink different tax bases.
- Check FICA against the wider base: gross minus pre-tax health premiums, with the 401(k) still in. Social Security should stop once your year-to-date wages pass $184,500 in 2026.
- For federal withholding, subtract premiums, the 401(k) and your standard deduction, then think in marginal slices — not one rate on everything.
- Do the state line last, on the state's own terms, then compare net against the calculator below — a mismatch usually traces to a local tax, a post-tax item, or a W-4 setting.
A stub looks like a bill. Read in order, it's a flowchart: one gross figure, filtered through layers with their own rules. Once you see which base each layer uses, the bottom line stops being a surprise and becomes arithmetic you can check.
The Verystep Paycheck Calculator follows the same order this guide describes — pre-tax deductions off first, FICA on the wider base, federal tax on what remains after the 2026 standard deduction, then your state's own structure — and prints every line, so you can hold it against your stub. It's an estimate only, not tax advice, and it runs in your browser: your salary never leaves your device.
Last verified November 3, 2026 — tax year 2026 figures as used by the calculator below: federal standard deductions and brackets per IRS Rev. Proc. 2025-32, Social Security wage base $184,500 (SSA), FICA rates per IRS Topic No. 751, 401(k) limit $24,500 per IRS Notice 2025-67. Estimate only — not tax or financial advice.
Frequently asked questions
Why is my take-home pay so much lower than my salary?
Because salary is gross — the figure before the queue. Pre-tax deductions, FICA at 7.65%, federal withholding and (in most states) state tax each take a slice, on different bases. In this guide's example, an $85,000 California salary becomes $59,647.06 once a 6% 401(k), health premiums and all four tax lines are counted.
Does a 401(k) contribution reduce Social Security and Medicare tax?
No. A traditional 401(k) deferral reduces the income your federal — and usually state — income tax is calculated on, but Social Security and Medicare are charged before the deferral is subtracted. Pre-tax health premiums are different: they generally escape FICA too.
When does Social Security tax stop during the year?
Social Security's 6.2% applies only up to an annual wage base — $184,500 for 2026. Once year-to-date wages pass that cap, the 6.2% stops until January. Medicare's 1.45% has no cap, plus an extra 0.9% above $200,000 single ($250,000 married filing jointly).
Why does the same salary pay more in Texas than in California?
State tax. Texas has no broad-based tax on wages in 2026, so its state line is $0. California runs graduated brackets off its own $5,900 standard deduction — $2,807.52 on this guide's $85,000 example. Federal tax and FICA are identical in both.
Is the tax on my pay stub my final tax bill?
No — stub income tax is withholding, an in-year estimate shaped by your W-4. Your actual tax is settled when you file: over-withhold and you get a refund, under-withhold and you owe. A refund doesn't mean the stub was wrong; the estimate simply ran ahead of the final bill.
More guides
PMI Explained: What It Is and When It Drops Off (80% / 78%)
You pay the premium, the lender holds the protection — and there are two different doors out, at two different percentages. Most borrowers only ever hear about one of them.
Why Damaged QR Codes Still Scan: Error Correction Explained
The torn poster still scans, the scuffed label still scans. That’s not scanner magic — it’s spare data, built into the grid before the code was ever printed.
Hex, RGB, HSL — and the Contrast Ratio Your Text Needs
Three formats, one colour — and a fourth number, the contrast ratio, that none of the three will tell you. That’s the one your readers feel.