Verystep Guides Verystep Guides
How to Project Compound Growth (and Read the CAGR Mode)
This calculator does two jobs in one place: it projects a balance forward at a rate you set, and it works backwards from two balances to the steady rate that links them.

Use standard mode when you know the starting amount, the monthly contribution, the annual interest rate and the number of years, and you want the future value. Use CAGR mode when you already know a starting value and an ending value and you want the single steady annual rate that would turn one into the other. The skill is not filling in the fields. It is reading the split afterwards: how much you put in, how much interest the run added, and what changes when you move a single field.
Two modes, two different questions
If you already know how compounding works, skip the theory — this guide stays on operation. One line is enough as a pointer: each period, interest is worked out on the balance so far, not just on the first deposit. Everything below is about entering numbers in the right mode and reading the output in the right order.
Standard mode looks forward. You supply the rate, so the result is only as steady as that rate is. CAGR mode looks back at a finished span. You supply the two values, and the tool returns the steady annual rate that connects them. Pick the mode before you type anything, because the fields change with it.
Run the calculator in seven steps
Open the Compound Calculator and work down this list in order. Do not jump between modes mid-run.
- Open the Compound Calculator and pick the mode first — standard projection for a future value, or CAGR if you already have a start value, an end value, and a time span.
- In standard mode, enter the initial investment, monthly contribution, annual interest rate, and years, using the rate you want to test rather than a rate you hope for.
- Set Compounds to Monthly, Quarterly, or Yearly to match how interest is credited, then check that the years field is a whole span and not months typed in by mistake.
- Read the future value, then read total contributions and total interest separately so you can see how much of the ending figure you put in yourself.
- Change one field at a time — rate, then years, then monthly contribution — and note how the future value moves after each single change.
- In CAGR mode, enter the starting value, ending value, and years, then read the CAGR as the steady annual rate that would connect those two values.
- Write down the inputs beside each result before you compare runs, and treat every projection as a steady-rate illustration, not a forecast of what will happen.
Step four is the one people skip. A future value on its own tells you little. The split tells the story: contributions are money you supplied, interest is what the run added, and the balance is the two together.
A worked run: $10,000, no contributions
Start with the plainest case. Initial investment $10,000. Monthly contribution zero. Annual interest rate 6%. Years 20. Compounds set to Yearly. The calculator returns a future value of $32,071.35. Read the split: you contributed $10,000, so about $22,071 of that ending figure is interest added across the twenty years. That clean split makes this a good first check — if your screen shows a different total, look at the compounding setting and the years field first.
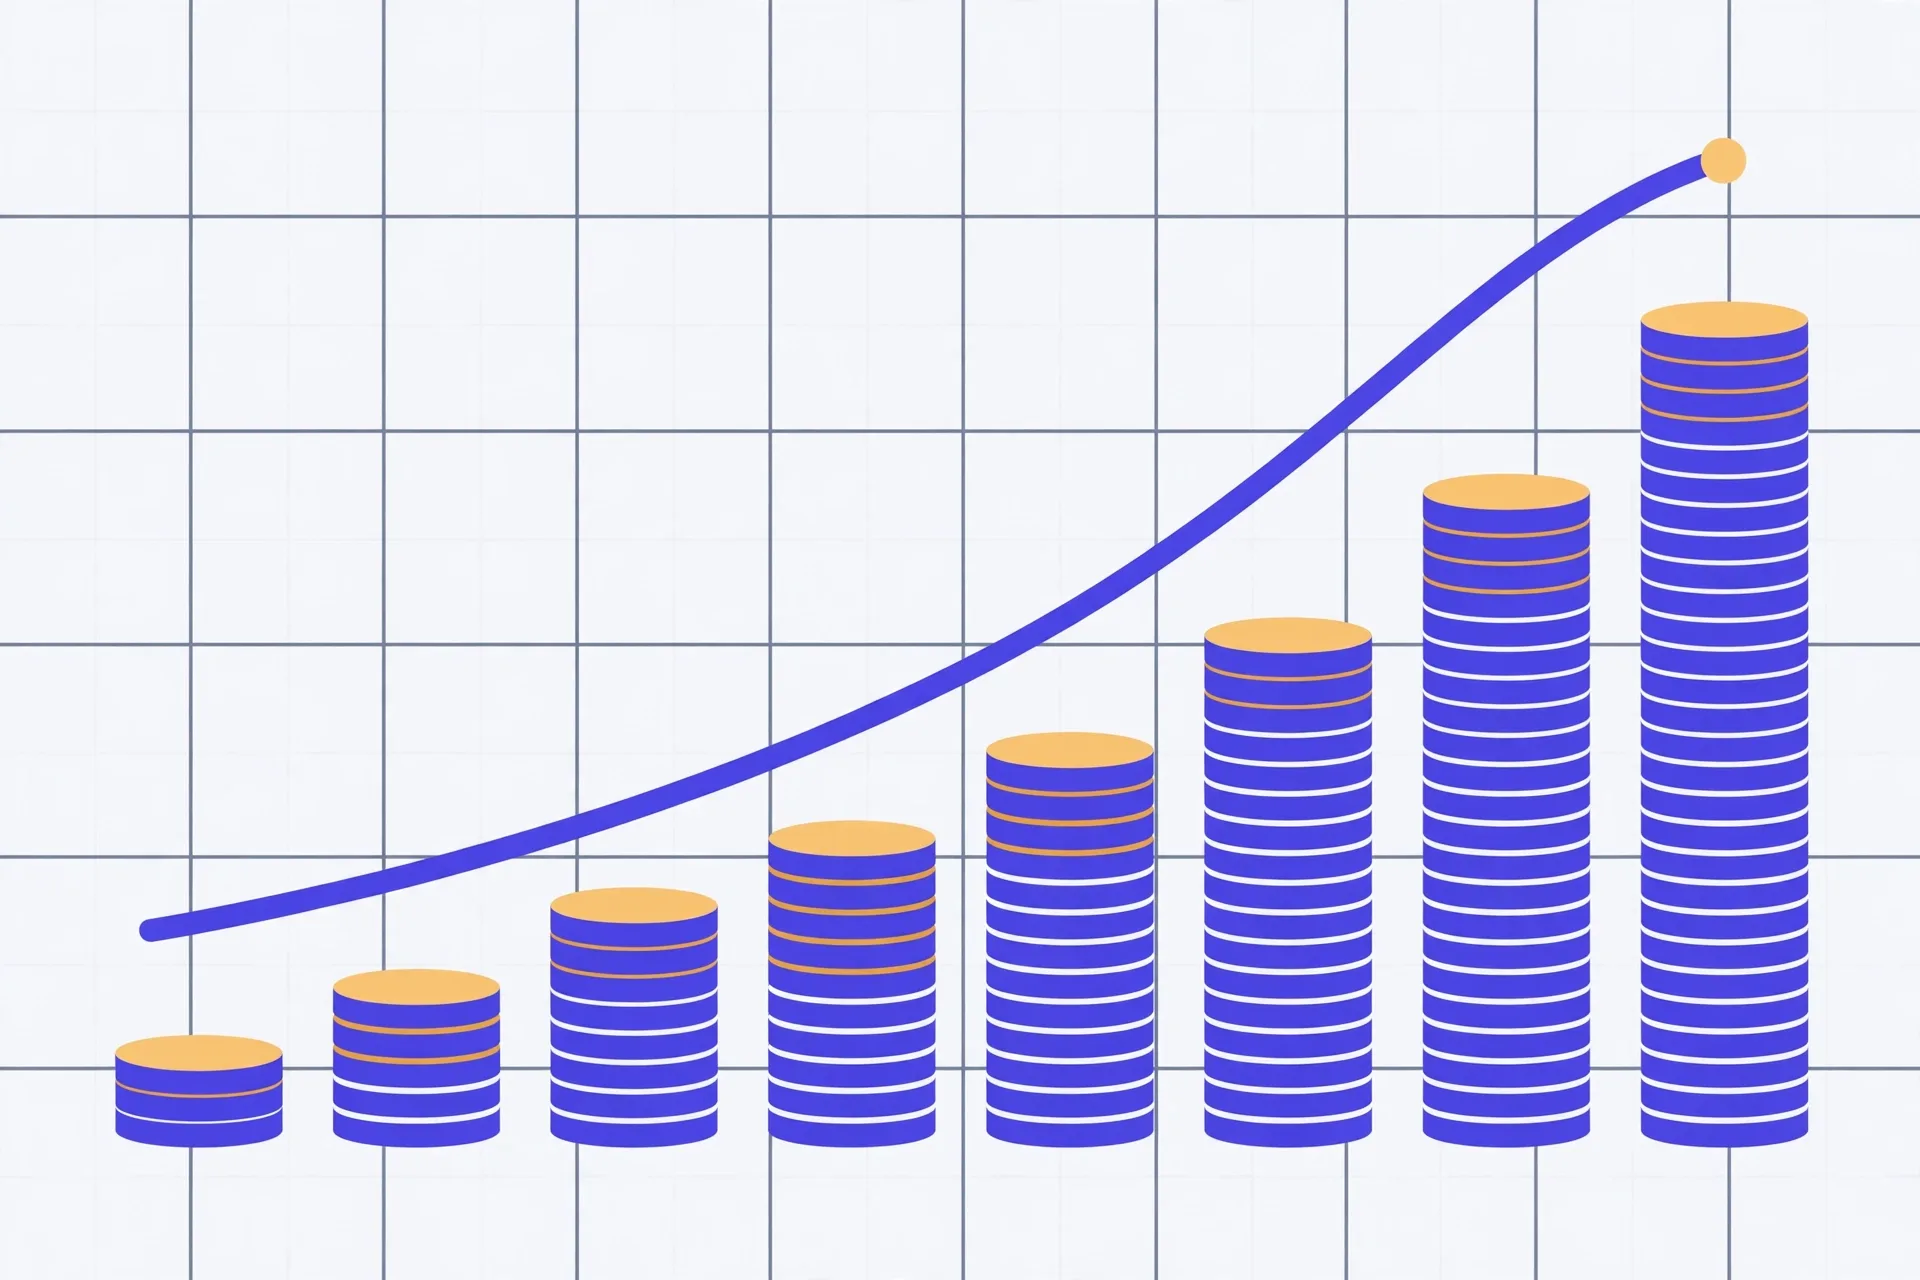
Now change one field. Switch Compounds from Yearly to Monthly and leave the rest alone. The future value edges up a little, because interest is credited more often and starts earning on itself sooner. The move is small at 6% over this span. Frequency matters, but rarely as much as the rate, the years, or the amount you add each month.
A worked run with monthly contributions
Reset the fields. Initial investment $5,000. Monthly contribution $200. Annual interest rate 7%. Years 15. Compounds set to Monthly. The calculator returns a future value of $77,637.19. Read the split: your contributions are the $5,000 at the start plus $200 a month for 180 months, which is $36,000, for $41,000 contributed in total. So about $36,637 of the ending figure is interest. Write both numbers down.
This is the run most people actually need, because most balances grow from regular additions, not from a single deposit left alone. Raise the monthly contribution and the ending figure climbs in a fairly straight way. Raise the rate and the climb bends, because the higher rate applies to a balance that is itself getting larger. Change them one at a time or you will not know which lever did the work.
Reading CAGR mode without misreading it
Switch to CAGR mode. You need three things: a starting value, an ending value, and the years between them. First example: $10,000 growing to $17,908.48 in 10 years gives 6.00% CAGR. That 6.00% is not a claim that the balance rose by exactly that amount every year. It is the one steady rate that, applied each year for ten years, lands on the same ending value. Second example: $8,000 to $12,500 in 7 years gives 6.58% CAGR. Real growth almost never arrives that smoothly.
Use CAGR for comparison, not for storytelling. Two holdings over different spans cannot be compared by total growth alone — 40% over ten years and 40% over four years are very different paces. Their CAGRs can be compared directly, because both are rates per year. Keep the limit in mind, though: a CAGR hides the ride. A steady climb and a wild swing can share the same start, end and CAGR.
Steady rates, common slips, and what a projection is not
Every figure in this guide assumes a steady rate for the whole span. Real returns vary year to year, and fees, taxes and inflation are not in these fields. A projection is a clean illustration of a mechanism — what happens if this rate held — not a promise about any account, fund or market, and not advice about where to put money. Test a lower rate beside your first run and see how much of the result survives.
Three slips account for most wrong answers. First, typing months into the years field, which turns a 15-year run into a 180-year one. Second, leaving a monthly contribution in place from a previous run. Clear the fields between runs. Third, changing the rate and the years at once. One field, read the split, then the next field.
The Verystep Compound Calculator takes an initial investment, a monthly contribution, an annual interest rate, years and a compounding choice, and it also has a CAGR mode for a starting value, an ending value and a span of years. Enter the run from this guide first to check your reading, then change one field at a time with your own numbers.
Last verified November 16, 2026 — steps, fields and worked figures checked against the Verystep Compound Calculator and standard compound growth math.
Frequently asked questions
What is the difference between standard mode and CAGR mode?
Standard mode looks forward: you enter an initial investment, a monthly contribution, a rate and years, and it returns a future value. CAGR mode looks at a finished span: you enter a starting value, an ending value and years, and it returns the one steady annual rate that connects them.
Why does switching Compounds from Yearly to Monthly change the result only a little?
Because the rate and the span stay the same — only the timing of when interest is credited changes. Crediting monthly lets interest earn on itself a bit sooner, so the ending figure edges up. The gap is small next to adding a year or raising the rate.
My future value looks far too large. What should I check first?
Check the years field. Months typed in as years is the most common cause — 180 in that field runs the projection for 180 years. Next, check that a monthly contribution from an earlier run is not still in the field. Fix one thing, then run it again.
Does a CAGR of 6.00% mean the balance grew 6% every year?
No. It means a steady 6.00% each year would produce the same ending value over that span. In the worked example, $10,000 growing to $17,908.48 in 10 years gives 6.00% CAGR, but the actual yearly moves could have been uneven. CAGR smooths the path so spans can be compared fairly.
Can I use this projection as a forecast for my own savings or investments?
No, and the tool does not present it as one. The math assumes the rate you typed holds steady for every year, with no fees, taxes or market swings. Real returns vary. Use the projection to see how rate, time and contributions interact, and test a lower rate alongside your first run.
More guides

How to Use an Auto Loan Calculator to Compare Two Offers
Two dealers can quote payments that look almost identical and still be selling you loans that cost hundreds of dollars apart. The calculator shows you where the gap hides.

How to Build a Debt Payoff Order: Avalanche vs Snowball, Step by Step
Paying extra money toward debt only works if the extra money has a target. This guide builds that target: an ordered list, made two different ways, so you can see exactly where each spare dollar goes.
How to Work Out What an Appliance Costs to Run
An appliance cost is three numbers multiplied together — watts, hours, and the price of a kilowatt-hour. Get those three right and the daily, monthly and yearly figures take care of themselves.